
It’s been an adventurous quarter in the technology markets – to say the least. Just two weeks ago, tech-dominated Nasdaq Composite was down 10% from its summer “AI high,” with fears about rising interest rates, the economy, and global conflicts weighing on the economy. It has since rallied.
Earnings season, a Fed meeting, and other factors have added volatility to the mix. If you dig a little deeper into cloud technology, it’s a little … uh … cloudy. Earnings seasons helped shine more light on what’s going on, with some companies showing strength and others falling behind.
Microsoft emerged once again as one of the stronger players in cloud, as it has adeptly navigated economic turbulence and taken the best advantage of the strongest place in the market – artificial intelligence (AI). And networking continues to be an interesting way to play AI, as some networkers such as Arista, F5, and Juniper showed strength related to cloud infrastructure spending.
Recent reports from the cloud hyperscalers were conflicting. Microsoft cloud growth numbers were strong, ranging from 24%-28% year/year (y/y). Depending on how you measure it, Google’s cloud growth slowed dramatically to under 10% y/y, and Amazon’s numbers demonstrated a return to stability, with growth at 12% — the first time it hasn’t declined in four quarters. More on that later. Let’s dive into some numbers.
Networking as an AI Play – Arista Hits a New High
Networking technology has emerged as an interesting play on AI. Although industry giant Cisco won’t report for another few weeks, market-leading networking companies including Arista Networks, F5, and Juniper Networks all posted strong results – with AI peppered into conference calls.
Shares of Arista Networks soared following Tuesday’s earnings report that beat Wall Street estimates, thanks to loosening supply constraints and growing sales from enterprise customers. And the networking specialist predicts that Ethernet and AI will play a key role in future success. Arista shares hit an all-time high on Wednesday.
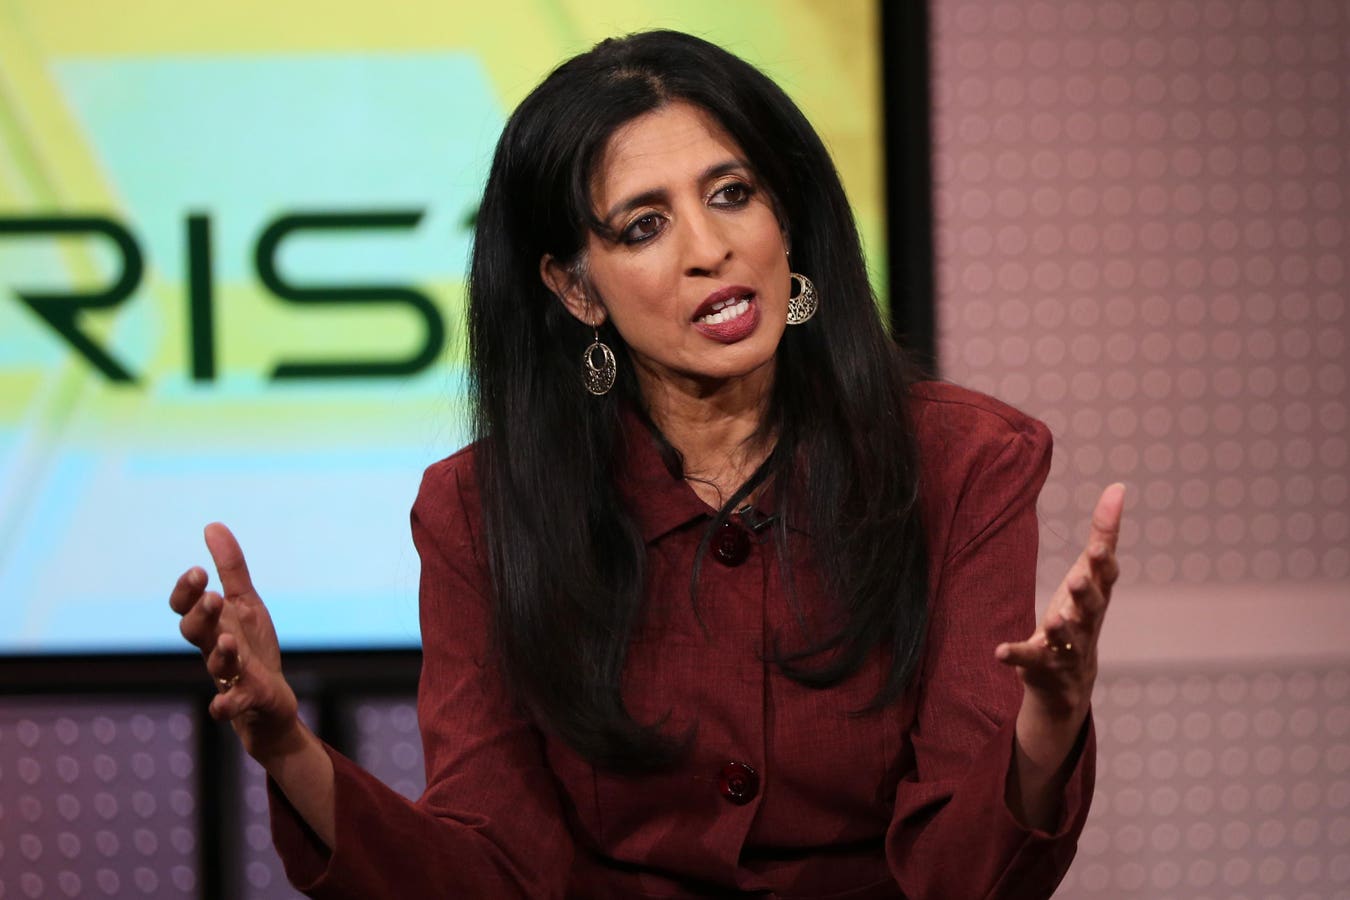
“Look, if you look back three years ago, we started seriously investing in the enterprise,” said CEO Jayshree Ullal on the earnings conference call. “[W]e have made an investment and seen a significant uptake in enterprise customers wanting to do business with Arista.”
Arista has become one of the leading AI plays among investors, who see its networking technology as key to connecting high-powered servers. AI is now so important that the company has created a new category it calls “cloud and AI titans.” Oracle has become a key customer in this category. This is no surprise, given Oracle’s growth, which comes in no small part from its generative AI service that trains large language models (LLMs) on processors from NVIDIA.
This past earnings report only solidifies the perception that Arista has become a leader in networking for AI, and it also points to the growing importance of networking in the cloud.
Ullal noted that “AI is going to become such an important component of all our cloud types that it’s now a combined vertical.”
There was other strength in the networking market, despite ho-hum earnings in most of the tech sector.
Enterprise networking player F5, which is also becoming a significant player in multicloud networking, reported revenue of $707 million for the quarter, compared to analyst estimates of $701 million. The company reported quarterly earnings of $3.50 per share, beating consensus estimates of $3.21. This compares to earnings of $2.62 per share a year ago. Shares have gotten about a 4% bump in the past week and are up 7% year-to-date.
Juniper Networks, which sells into similar markets to Arista, also reported a pretty good quarter, boosting its shares. It posted revenues of $1.4 billion for the quarter ended September 2023. Although that was slightly lower than last year’s number, it surpassed consensus estimates. This compares to year-ago revenues of $1.41 billion. The company has beaten revenue estimates over the last two quarters. On an adjusted basis, the company earned 60 cents per share, compared with estimates for a profit of 55 cents. Juniper shares are up about 10% over the past week, but they have still been hovering near the year’s low and they are down 16% year-to-date.
Another recent strong networking performer, Extreme Networks, posted strong results but suffered a bit of a setback as revenue guidance came in light. The company met earnings and revenue expectations, but the company lowered its 2024 revenue estimates, even though it still expects to increase earnings per share. Company officials cited inventory constraints and more cautious customers as reasons for the dialed-back outlook. Shares fell about 10% this week.
Cloud Was Uneven
Meanwhile, the earnings reports from the cloud hyperscalers were more uneven. Microsoft and Alphabet’s earnings couldn’t be more divergent. Microsoft’s impressed and Google’s disappointed, leaving the impression that Microsoft could be increasing its lead over Google in both the cloud and AI segments.
Microsoft reported revenue of $56.5 billion, up 13% from a year ago, and $2 billion ahead of analyst consensus estimates. The company reported EPS of $2.99, ahead of EPS estimates of $2.65. The Azure cloud business grew 28%, ahead of the company’s forecast for growth of 25% to 26%. Microsoft cloud revenue was $31.8 billion, up 24%.
Microsoft attributes its cloud success to a general infusion of artificial intelligence across all its products. “Higher than expected AI consumption contributed to revenue growth in Azure,” said CFO Amy Hood on the earnings call, referring to the addition of multiple foundation models to Azure. Azure sales also benefited from the addition of Oracle databases to the cloud service.
Alphabet, Google’s parent company, reported numbers that beat estimates — but shares sold off on slower cloud growth and a disappointing outlook for advertising. Google reported revenue of $76.69 billion, up 11% from a year ago, beating a forecast of $76 billion. The company reported EPS of $1.55, nine cents better than estimates. Google Cloud revenue in the quarter was $8.4 billion, up 22%, but that fell short of analyst consensus estimates of $8.6 billion. It’s also a marked slowdown from the growth of 28% in the previous quarter.
Google’s slowing growth rate indicates that Microsoft still appears to be taking share from Google and extending its lead in cloud infrastructure and services.
Amazon, on the other hand, gave investors good news, which has lifted shares 10% over the past week. Amazon reported cloud growth of 12% for its third quarter of 2023, which is the first time in four quarters that its growth rate hasn’t declined. Its growth rate in the second quarter was also 12%.
Amazon reported $143.1 billion in revenue, up 11% y/y; $11.2 billion in operating income, up 343% y/y or $8.7 billion; and $20.2 billion in trailing 12-month free cash flow adjusted for equipment finance leases, up $41.7 billion versus the comparable period last year.
CEO Andy Jassy had some upbeat things to say about the fourth quarter:
“[W]e’re encouraged by the strong last couple of months of new deals signed. For perspective, we signed several new deals in September with an effective date in October that won’t show up in any GAAP reported number for Q3, but the collection of which is higher than our total reported deal volume for all of Q3.”
Summing things up: Recent earnings have so far been mixed, but not a disaster. The cloud market appears to be absorbing slower growth and higher interest rates as companies focus on cost optimization.
There is still cloudy visibility for 2024 (pun intended), as the market remains concerned about many issues, including global conflicts in Israel and Ukraine, slow growth in China, high interest rates, and overall business uncertainty. The fact that the U.S. Federal Reserve held interest rates steady in its Wednesday meeting was a welcome relief to the market, which responded by rallying.
Read the full article here